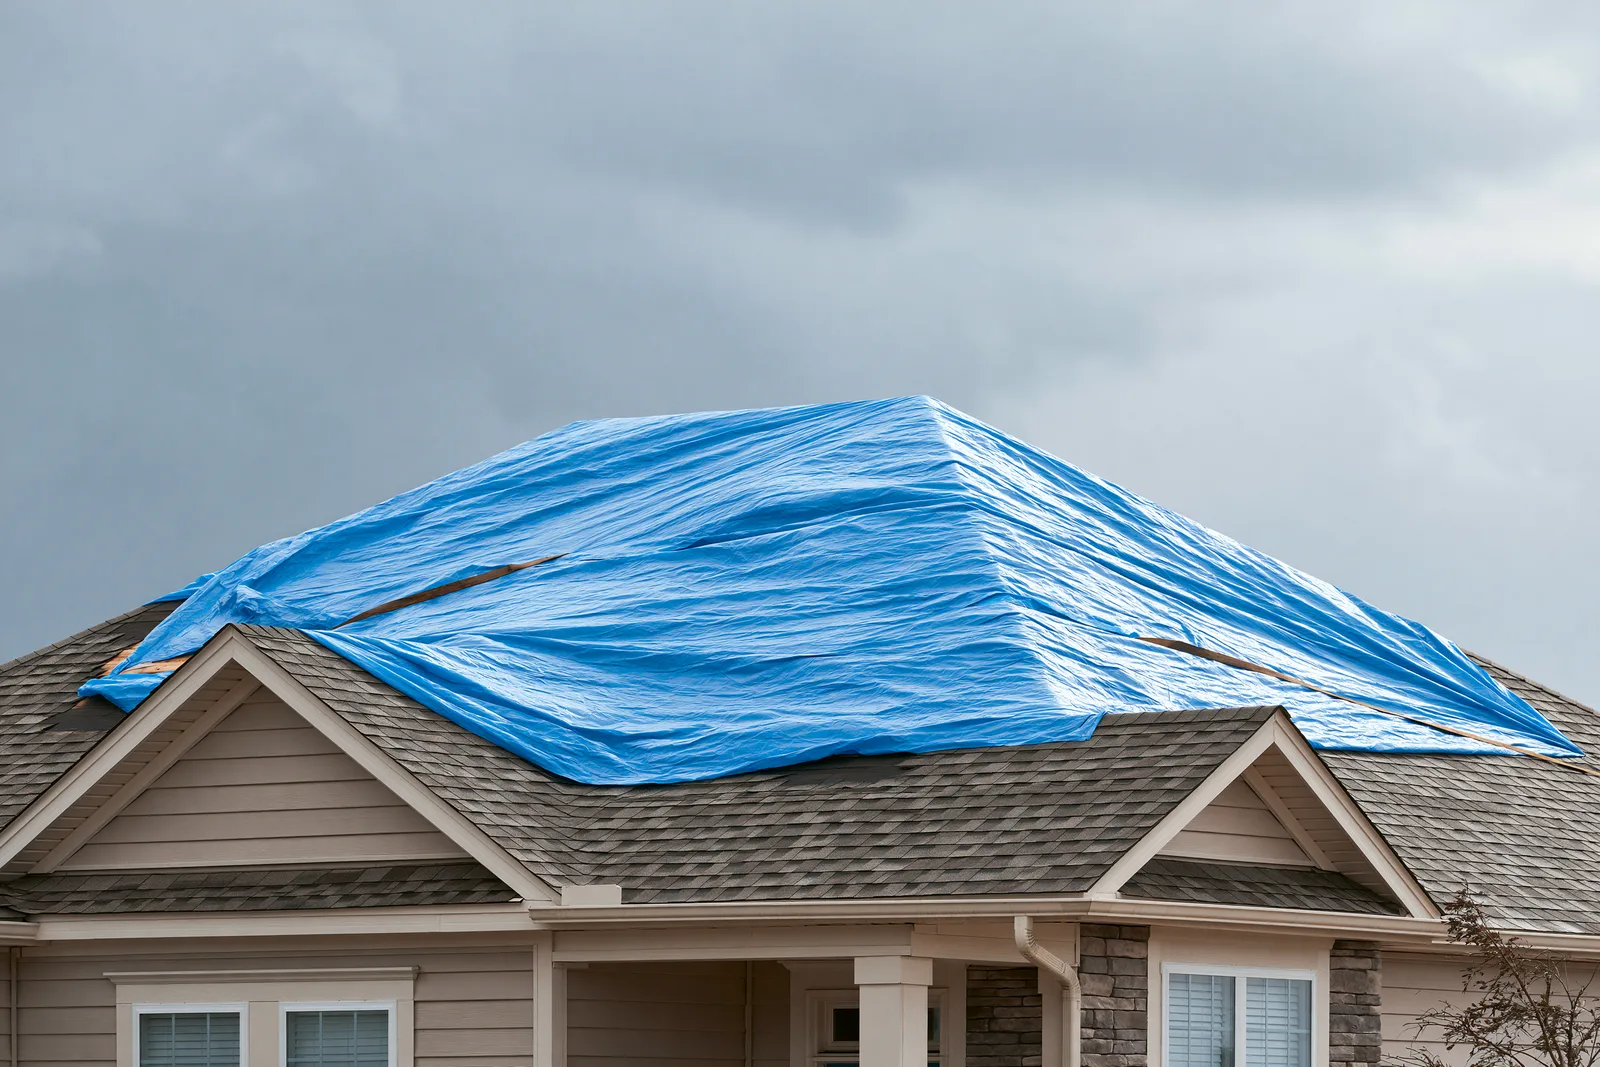
Roof insurance claims in Arkansas
Understand the deductible, depreciation and roof scope before treating an approved amount as money already in hand.
A closer look before a big decision.Free inspection. No project commitment.
Roof claims: damage, coverage and payment
The roof needs an assessment of its damage and repair options. Your insurance policy answers a separate question: which losses are covered and how payment is calculated. A free roof inspection does not by itself establish that a claim is payable.
The Arkansas Insurance Department’s post-storm guidance advises documenting damage, limiting further loss and contacting the insurer. Keep roof access and temporary repairs with people equipped to do them safely. The insurer can explain the requirements for your specific claim.
Roof damage, inspection and the claim decision
| Claim step | What to establish |
|---|---|
| Establish the roof condition | A free inspection helps distinguish storm damage, wear and repair needs. Nearby storm reports do not prove a loss at the house. |
| Protect and document | Stay safe, preserve useful photos taken from accessible places and keep receipts for necessary temporary protection. Follow the insurer’s instructions before permanent repairs. |
| Understand the deductible | If the covered damage is below the deductible, there may be no claim payment. A percentage deductible is based on the policy’s specified amount, not automatically a percentage of the roof invoice. |
Roof claim payment example: deductible and depreciation
Illustrative arithmetic only. Assume a covered $15,000 replacement scope, $4,000 recoverable depreciation and a $2,000 deductible. The first payment is $9,000. If the policy requirements are met, a later $4,000 payment would bring the insurer’s total to $13,000, leaving the $2,000 deductible.
The amounts are invented to explain the arithmetic, not to predict a claim or the cost of a Fort Smith roof. The example assumes all of that replacement scope is covered; upgrades or other uncovered work would add to the owner’s cost.
| Step | Example amount | Meaning |
|---|---|---|
| Approved replacement amount | $15,000 | The insurer’s covered scope in this example. |
| Initial payment | $9,000 | $15,000 less $4,000 withheld depreciation and the $2,000 deductible. |
| Potential later payment | $4,000 | Recoverable only when the policy’s completion and documentation conditions are met. |
| Owner’s deductible | $2,000 | The owner’s share remains; it is not waived by the example. |
Actual cash value, replacement cost and uncovered work
Actual cash value coverage
Depreciation reduces the covered value. Under an ACV-only roof settlement, that reduction may not be recoverable after the work.
Replacement cost coverage
An initial payment can withhold depreciation. Later payment depends on the policy, completed work and required evidence; it is not an unconditional second check.
Other scope differences
Upgrades, uncovered repairs, limits and exclusions can leave costs beyond the deductible. The contractor scope and insurance allowance may need reconciliation.
Arkansas Roof Claim FAQs
Does a free roof inspection mean I should file a claim?
No. It helps establish what is wrong with the roof. The type and cost of damage, deductible and policy terms affect the claim decision.
Can a roofer promise insurance will buy my roof?
No. The insurer determines coverage and payment. A roofer can explain the damage and proposed work, without guaranteeing the claim result.
What if the repair is not an insurance loss?
The roof still needs a scope that fits the physical problem. A repair may address a local failure; replacement is a different project. Start with the roof repair explanation.
Why might a replacement-cost claim begin with a smaller payment?
An insurer may initially deduct depreciation and release eligible recoverable depreciation after the required repair or replacement evidence is provided. The policy and claim requirements control that later payment; it is not an unconditional second check.
Get the roof damage assessed
Start with a free inspection of the roof and the work it may need. Keep the insurance payment decision tied to your actual policy.